Possible: Fast Cash & Credit

- 27.66K Reviews
- 4.4
- Downloads
- 1,000,000+
 Analysis by Mobxio
When an unexpected expense lands between paydays, I want a clear way to handle it—not another financial product that leaves me guessing about repayment. Possible: Fast Cash & Credit is a finance app from Possible Finance - A Public Benefit Corporation, built around borrowing and credit-building. Its appeal is easy to understand, but I’d treat it as a tool for a specific short-term need, not a substitute for a budget or a dependable emergency fund.
What free access does—and does not—tell you
The app is free to download, which makes trying it out different from paying for a budgeting subscription or buying a financial service upfront. That is the verified part of the cost story. Free access should not be confused with a promise that borrowing itself has no cost: I would review the offer and repayment terms shown for my own application before accepting anything. The app’s price to install and the total cost of a loan are separate questions.
That distinction matters because the most important decision is not whether I can open the app without paying, but whether a particular advance fits my next few weeks of cash flow. I would check the amount offered, the payment schedule, and any applicable costs in the app before moving forward. If I can’t comfortably explain how each repayment fits around rent, utilities, food, and other obligations, I would pause rather than borrow just because the process is convenient.
Where the value can show up
Possible is most useful when a relatively small, time-sensitive expense cannot wait and I have a credible plan for paying it back in installments. That could mean dealing with an urgent bill before a paycheck arrives, rather than putting the expense on a high-interest card or risking an overdraft. The value is practical: spreading repayment can make a short-term cash gap easier to manage than facing one large payment, provided the schedule is genuinely affordable.
There is also a potential longer-term reason to consider it: the app connects repayment with credit-building. I’d view that as a possible side benefit, not a guaranteed result or a reason to take out a loan I don’t need. Credit outcomes depend on what is reported and on a person’s broader financial history, so I would keep making every other payment on time and check my own credit reports rather than assuming this one product will transform a score.
Tradeoffs to think through before applying
A quick application can feel reassuring when an expense is pressing, but speed doesn’t remove the obligation that follows. An installment plan still claims part of future income. Before borrowing, I’d map the scheduled payments against my actual paydays and leave room for essentials and irregular bills. If the plan only works when nothing else goes wrong, it is probably too tight.
Rescheduling can be useful when circumstances change, but I would not build a borrowing plan around the expectation that I can always move a payment. Flexibility is a safety valve, not extra income. I’d also compare the in-app offer with the real alternatives available to me—asking a biller about a due-date change, using savings, or checking a lower-cost source of credit—because the best option depends on the urgency and total repayment cost.
More Stories to Explore
Uber Eats After the OS Update: Better Tracking, More Permission Friction
Google Chrome Wins App of the Week for Making Everyday Browsing Easier
Wordscapes Makes the Five-Minute Break Feel Complete
Switching to Audible Means Building a Listening Habit
Moovit Review: A Better Transit Guide When Your City Has the Data
Brave’s Privacy Has Limits Set by Android and iOS
Getting Started with the App
First things first, downloading the app was a breeze. Available on both Android and iOS, Possible: Fast Cash & Credit ensures you’re not left out regardless of your device preference. Once installed, the setup process is straightforward. You simply need to enter some basic information, and you’re good to go.
The interface is clean and user-friendly, which is something I really appreciate. No clutter, no confusion—just a simple design that guides you through each step. And let’s be honest, when you’re in a rush to sort your finances, the last thing you need is a confusing app.
How It Works
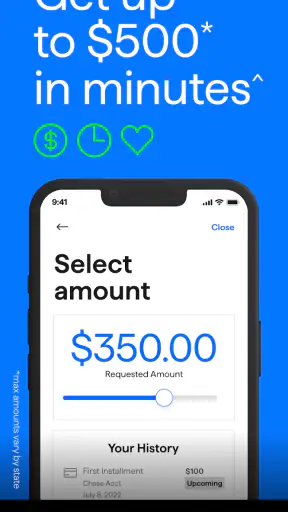
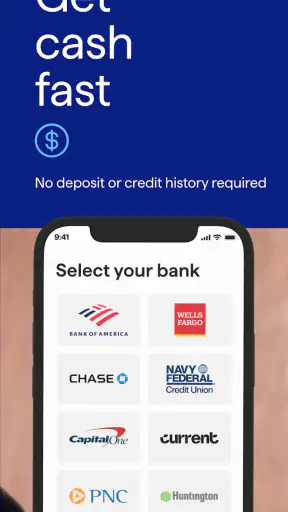
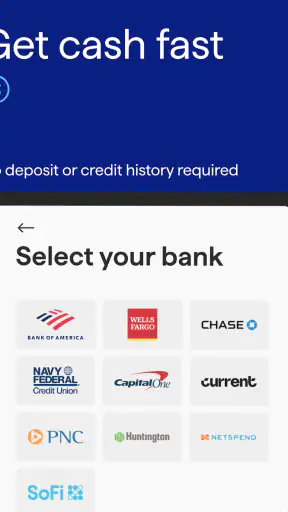
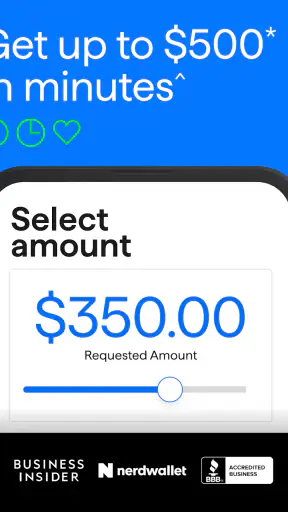
So, how exactly does it work? The app offers small loans that you can repay over time, which is fantastic if you’re trying to avoid those nasty overdraft fees or high-interest credit cards. What’s cool is that you don’t necessarily need a perfect credit score to get approved. The app looks at other factors too, like your income and bank transactions.
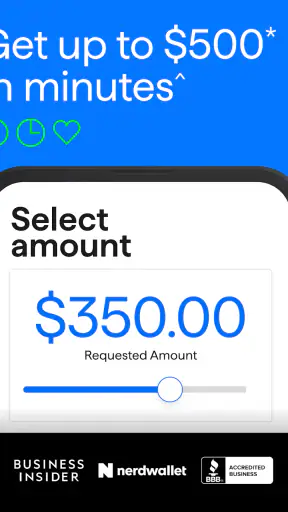
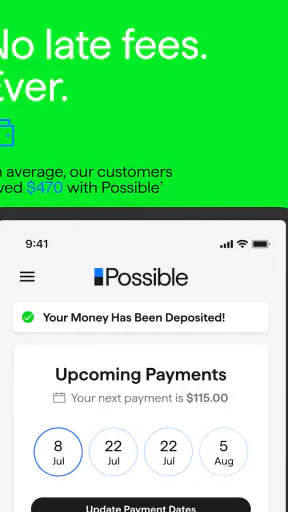
Once approved, the money lands in your account pretty swiftly. I found this particularly handy when I needed to cover an unexpected bill. You know those moments when life throws a curveball? Yeah, this app has your back.
Repayment and Flexibility
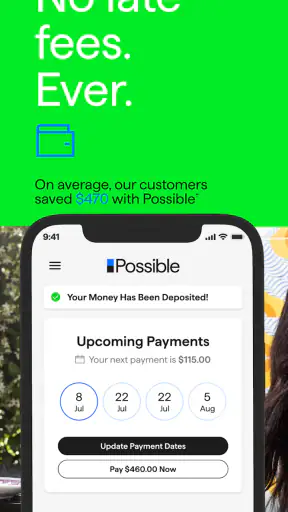
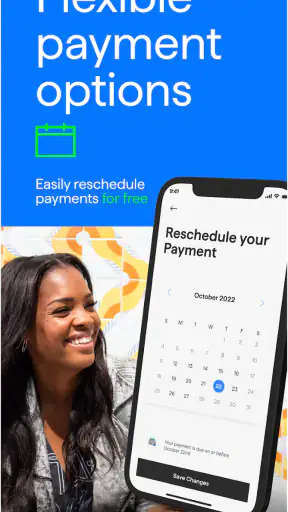
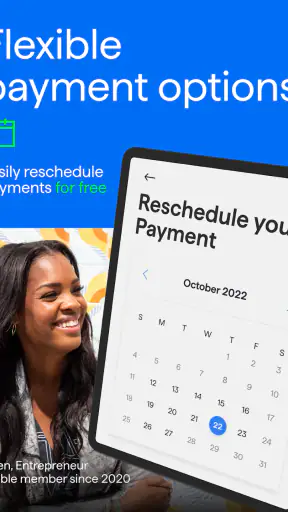
Repayment is where Possible: Fast Cash & Credit really shines. The app allows you to repay the loan in installments, which is much easier on the wallet compared to paying it all at once. Plus, if you ever find yourself struggling to meet a payment, the app provides options to reschedule.
This flexibility is a major bonus, and it feels like the app genuinely understands the ups and downs of managing finances. It’s not just about lending you money; it’s about helping you handle it responsibly.
Building Your Credit
Another sweet perk is the opportunity to build your credit score. As you repay your loans on time, you’ll slowly but surely see improvements in your credit report. It’s a win-win situation if you're looking to boost your financial health in the long run.
How I’d use it in an ordinary cash crunch
Imagine a necessary car repair arrives just before payday, and postponing it would make getting to work difficult. I’d first confirm that the repair is urgent, ask the mechanic whether payment timing can be adjusted, and check whether savings can cover some of it. If I still needed to borrow, I’d use Possible to compare the actual offer with the cost and timing of those alternatives—not accept the first available amount by default.
Then I’d write the repayment dates into the same calendar I use for rent and other bills. That small step is easy to overlook when money arrives quickly, but it helps show whether installments collide with another large expense. I’d also keep the loan amount tied to the repair rather than treating any unused portion as extra spending money. The app is most useful when it solves one defined gap, not when it quietly expands the month’s budget.
What to check before committing
Before submitting an application, I’d make sure the personal and financial details I enter are accurate and that I can access the bank information needed to complete the process. Since income and bank transactions can matter to an application, a recent change in employment or deposit timing may affect how well the picture reflects my current situation. If my finances have just shifted, I would take that into account instead of assuming an earlier pattern still applies.
I’d read the offer screen carefully and save the payment dates somewhere I can find them later. A useful test is to ask: if my next paycheck is smaller than expected, can I still cover essentials and the scheduled payment? If the honest answer is no, I’d look for a payment extension from the biller, a trusted source of help, or another lower-cost option first. This is a practical safeguard, not a reason to assume rescheduling will always be available or cost-free.
People also often wonder whether applying means they will automatically receive cash. It does not: an application and an approval are different steps, and an offer depends on the assessment made for that person. I would make plans only after seeing the actual decision and terms, rather than counting on money that has not been approved. If the expense has a hard deadline, I’d keep a backup plan in mind while applying.
How it compares with familiar alternatives
Compared with a credit card, an installment loan can make the repayment path easier to see because payments are scheduled rather than left to a revolving balance. That structure may help someone who prefers a defined plan, but it is not automatically cheaper; the total cost and the borrower’s ability to make each payment matter more than the format. A card with a low-cost promotion or an existing balance-management plan could be a better fit for some people, while carrying an expensive revolving balance could be the worse choice.
A bank overdraft is another common fallback when a bill arrives before income. It may require less setup, but the consequences depend on the account’s terms and how far the balance goes below zero. Possible offers a separate borrowing route with installments, yet I would compare the exact repayment burden rather than assume one approach is always superior. If I can delay a nonessential purchase or move a bill’s due date without borrowing, that is often simpler than adding a new obligation.
For someone whose real need is to understand where money goes each month, a budgeting app or a conversation with a nonprofit credit counselor may be more useful than a loan app. Those options do not solve an immediate cash shortfall in the same way, but they can address recurring gaps without creating another repayment schedule. Possible makes more sense when the need is specific and temporary; it is not the tool I’d choose to repair a budget that remains short every month.
Who is likely to get the most from it
I can see this being useful for someone with a short-term bill, income that is expected soon, and enough room in the coming budget to meet the installments. It may also appeal to a person who wants a structured repayment route and is interested in credit-building, while understanding that credit improvement is not something to count on as an immediate or guaranteed outcome.
I’d be cautious if pay varies sharply, existing debt already takes most available income, or the expense is part of a repeating pattern. Borrowing to cover one surprise can be a bridge; borrowing repeatedly to cover groceries, rent, or routine bills can signal that the underlying budget needs attention. In that situation, adding installments may make the next month harder rather than easier. Someone who needs a large, long-term loan should also compare products designed for that purpose instead of expecting a short-term cash app to meet every need.
Possible is free to install, rated for Everyone, and has a 4.4 average from around 58,000 ratings. Its current version is 2.3.7, and it has been available since January 25, 2018. More than a million installs suggest it has reached a broad audience, though popularity alone cannot tell me whether an individual offer is affordable. I’d use the public reception as context, then make my decision based on the terms presented to me and my own ability to repay.
My practical verdict
Overall, Possible: Fast Cash & Credit is worth considering when I need a clearly defined amount for a near-term problem and the installment plan fits comfortably into my next budgets. I like the straightforward approach described in the app and the chance to build credit through repayment, but neither convenience nor a possible credit benefit should replace a careful look at cost, timing, and alternatives.
Possible Finance - A Public Benefit Corporation is behind the app, and the combination of cash access and credit-building gives it a more focused purpose than a general budgeting tool. Still, it is not the right choice for every financial problem. I would skip borrowing if the repayment depends on optimistic assumptions, if the expense can be handled more cheaply another way, or if I’m using new credit to patch the same recurring shortfall. Used selectively and with the offer reviewed first, it can be a helpful option; used without a repayment plan, it can turn a short-term pinch into a longer one.
Possible: Fast Cash & Credit FAQ
What is Possible: Fast Cash & Credit used for?
Possible: Fast Cash & Credit is an app designed to provide quick access to small loans and help users build credit. It's ideal for individuals needing immediate financial assistance or those looking to improve their credit score over time by making timely payments.
How quickly can I access funds through the app?
Once approved, users can typically access funds within one to two business days. The app is designed for speed, ensuring that users can quickly receive the financial assistance they require without lengthy approval processes or excessive paperwork.
Is my data secure with Possible: Fast Cash & Credit?
Yes, the app uses industry-standard encryption and security measures to protect user data. Ensuring user privacy and data protection is a top priority, so you can feel confident that your personal and financial information is safe.
What are the eligibility requirements for a loan?
To be eligible for a loan, users must be at least 18 years old, have a valid bank account, and meet the app's minimum income requirements. The app also considers your ability to repay the loan, so approval may vary based on individual circumstances.
Are there any fees associated with using the app?
Yes, there are fees associated with taking out a loan, which are clearly detailed during the application process. It's important to review these fees to ensure you understand the total cost of borrowing and how it fits into your financial plan.
The Best Parts of Possible: Fast Cash & Credit
Things to Keep in Mind About Possible: Fast Cash & Credit